Executive Overview
The global data center landscape is undergoing an unprecedented paradigm shift. Propelled by the meteoric rise of artificial intelligence (AI), machine learning, and cloud computing, demand for digital infrastructure has reached historic highs. Yet, beneath the booming headlines of multi-billion-dollar investments and sprawling campus announcements lies a looming crisis: a widening chasm between speculative capacity pipelines and physical delivery capability.
For years, the data center sector has operated on robust forecasting models, confident that capital and customer interest would naturally translate into operational facilities. However, according to recent industry telemetry—including insights from the BCS Q2 2026 Data Centre Commercial Report—93% of industry respondents anticipate unyielding demand growth, while simultaneously bracing for perpetual supply chain volatility and severe labor shortages.
The industry’s competitive edge is no longer defined by who can forecast demand the most aggressively. Instead, success increasingly hinges on deliverability. Power availability, complex regulatory and planning requirements, shortages of specialist labor, utility grid constraints, and protracted manufacturing lead times for critical equipment are combining to place immense pressure on project programs. When these challenges strike simultaneously rather than sequentially, development schedules collapse, budgets bloat, and the foundational assumptions supporting investment cases begin to fracture.
This deep-dive investigation explores the shifting dynamics of data center development, analyzing why traditional project sequencing is failing, how cost certainty is tied directly to delivery execution, why European markets demand hyper-local strategies, and why roughly 30% of announced projects never break ground. Ultimately, the article outlines how the industry must evolve from optimistic announcements to disciplined execution strategies to weather the coming storm.
Detailed Chronology: The Evolution of Project Failure Points
To understand how modern data center projects derail, one must examine the lifecycle of a digital infrastructure development and the structural pressures eroding its timeline.
The Breakdown of Traditional Project Sequencing
Historically, data center developers followed a linear, predictable project sequence:
- Site Acquisition: Secure a strategically located plot of land with fiber connectivity.
- Power Confirmation: Secure a reliable, high-capacity electrical feed from the local utility.
- Design Finalization: Develop a mature architectural and engineering design tailored to specific workload profiles.
- Procurement & Construction: Procure long-lead equipment (generators, chillers, switchgear) and commence physical construction.
In contemporary markets, this linear model is broken. Driven by unprecedented demand, the foundational assumptions of this sequence—namely, that equipment, skilled labor, and regulatory approvals will be available on demand—are no longer reliable.
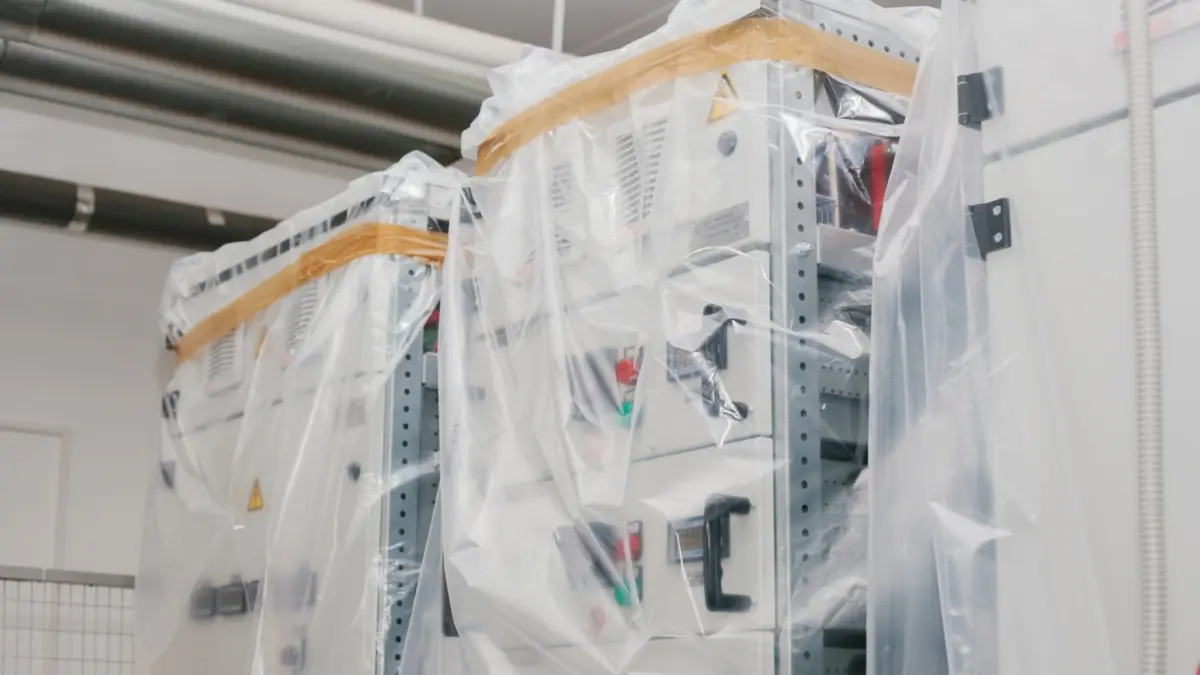
Long lead times for critical electrical and mechanical components are forcing developers to make procurement decisions much earlier in the lifecycle. Waiting for a design to reach 100% maturity before ordering equipment can delay delivery dates by quarters or even years. Conversely, committing to procurement too early restricts engineering flexibility, potentially locking a project into sub-optimal technical configurations or creating massive commercial exposure if workloads pivot toward higher-density AI deployments.
The Cascading Impact of Bottlenecks
When delays occur, they rarely happen in a vacuum. A delayed grid connection does not simply push back the operational go-live date; it extends preliminary site costs, disrupts financing terms, and strains client relationships. Similarly, missing a manufacturing slot for custom switchgear can force an emergency redesign, triggering cascading program shifts. Even when physical construction finishes on time, chronic shortages of specialist testing and commissioning engineers can leave multi-million-dollar facilities sitting idle, unable to be energized or safely handed over to tenants.
Consequently, modern data center delivery requires a simultaneous, cross-functional approach. Commercial, design, procurement, and program management teams must work in lockstep. Without robust governance frameworks, real-time market intelligence, and absolute confidence in the data driving decisions, projects quickly succumb to paralysis or catastrophic cost overruns.
Supporting Context & Metrics: Cost Inflation, Supply Chains, and Market Realities
The pressures facing the data center sector are quantifiable, systemic, and deeply rooted in macroeconomic and infrastructural realities.
Financial Realities: The 5-8% Cost Growth Trajectory
Inflation is frequently cited as the primary driver of rising project expenses, but cost overruns are almost always the visible symptom of an earlier failure in delivery planning. The BCS Q2 2026 Data Centre Commercial Report forecasts persistent annual cost growth of 5% to 8% through 2029. This sustained inflation is fueled by a cocktail of pressures: relentless compute demand, acute labor deficits, localized power constraints, and structural supply chain volatility.
| Challenge Factor | Primary Impact on Project Lifecycle | Associated Risk Level |
|---|---|---|
| Power Constraints | Delayed grid connections, reliance on temporary diesel generation, stranded assets. | Critical |
| Supply Chain Volatility | Extended lead times for long-lead equipment (transformers, generators, UPS systems). | High |
| Labor Shortages | Bottlenecks in specialized electrical, mechanical, and commissioning engineering. | High |
| Planning & Regulation | Protracted permitting timelines, environmental challenges, local zoning disputes. | Moderate-High |
Traditional benchmarking approaches—which focus strictly on historical construction rates or current material costs—are no longer sufficient. Cost benchmarking must now incorporate risk-adjusted variables: How long will a quoted price remain valid? What is the probability of a supply chain disruption for critical gear? Which procurement decisions must be made today to insulate the project against future cost shocks?
The European Paradox: Why Delivery Remains Hyper-Local
While capital flows globally, data center delivery remains an intensely local endeavor. Across Europe, there is no monolithic delivery model. Power availability, regulatory frameworks, environmental mandates, local labor markets, and municipal planning processes vary wildly not just by country, but by region and municipality.
For instance, a standardized blueprint that successfully accelerates development in secondary Nordic markets may face insurmountable regulatory hurdles or grid capacity blocks in core markets like Frankfurt, London, Amsterdam, Paris, or Dublin (the FLAP-D markets). While global developers prize consistency across multi-site portfolios, attempting to deploy a cookie-cutter strategy without accounting for local nuances is a recipe for project failure.
Early, deep local intelligence is non-negotiable. Developers must rigorously test their investment thesis against ground-level delivery conditions—ranging from local utility responsiveness to regional trade union availability—long before capital commitments become difficult or financially ruinous to reverse.
Official Statements and Industry Insights
As the data center community grapples with these structural realities, industry leaders and commercial reports are sounding a collective note of caution. The gap between ambition and execution is narrowing the field of viable players.
Experts note that while capital abundance was once the primary barometer of industry health, execution capability has claimed the crown. As highlighted in recent market analysis:
"The industry has become highly effective at forecasting demand. Its next competitive advantage will come through understanding deliverability."
This sentiment underscores a broader reckoning regarding how projects are communicated to stakeholders and investors. In an era where speculative announcements generate immense media attention, industry veterans emphasize that market communications must be anchored in operational reality:
"An announcement is not a delivery strategy. Around three in 10 announced data center projects do not reach construction. A credible project requires more than customer interest and capital. It needs a realistic power date, a clear planning route, access to specialists, an achievable procurement strategy, and governance that supports timely decision-making."
Furthermore, experts emphasize that project plans must evolve from static documents into dynamic, living commercial models. As market conditions fluctuate, leadership teams must routinely stress-test their power, procurement, labor, and cost assumptions. Only by shining a light on operational vulnerabilities can organizations transform uncertainty into manageable risk.
Future Outlook: Building a Resilient Data Center Pipeline
Looking toward the remainder of the decade and beyond 2029, the trajectory of the data center industry will be defined by discipline, innovation, and structural realism. The artificial intelligence boom is not a temporary spike; it is a fundamental restructuring of global compute requirements. However, the physical world cannot scale at the instantaneous pace of software innovation.
To bridge this gap and ensure that announced pipelines successfully transform into operational revenue-generating facilities, the sector must embrace several strategic imperatives:
1. Integration Over Silos
Engineering, procurement, construction, and commercial teams can no longer operate in isolated silos. Integrated project delivery models that align cost plans, technical programs, and power acquisition strategies from day one will drastically reduce the friction that leads to costly delays.
2. Advanced Risk-Adjusted Benchmarking
Cost planning must evolve beyond simple historical indexes. Forward-looking models must factor in localized supply chain vulnerabilities, utility lead times, and labor market liquidity to provide a true picture of project exposure.
3. Early Stakeholder and Utility Engagement
Developers must engage with transmission system operators (TSOs) and distribution system operators (DSOs) years—not months—before groundbreaking. Innovative power strategies, including behind-the-meter generation, microgrids, and co-location with renewable energy sources, will increasingly dictate which projects secure viable energization timelines.
4. Cultivating Specialist Talent
With skilled labor shortages identified as a permanent market friction point, leading organizations are investing heavily in talent retention, specialized training partnerships, and modular construction techniques that reduce the dependency on massive on-site workforces.
Conclusion
Demand will undoubtedly continue to dictate the grand scale of global digital infrastructure expansion. Yet, the defining narrative of the next decade will not be how much capacity the market demands, but how much capacity it can successfully deliver. By swapping speculative ambition for disciplined execution, local intelligence, and rigorous project governance, forward-thinking developers will separate themselves from the pipeline noise and secure a lasting competitive advantage in an increasingly constrained world.