By Christopher Tozzi
Technology Analyst
Executive Overview
For decades, the physical blueprint of the modern data center remained remarkably consistent. Operators planned their real estate, power distribution, and thermal management around a dependable baseline: roughly 10 kilowatts (kW) of sustained power per equipment rack. While high-performance computing (HPC) environments occasionally pushed these limits, they were treated as outliers—expensive, specialized anomalies managed by niche operators.
Today, that foundational metric is rapidly becoming obsolete. Driven by the relentless march of generative artificial intelligence (AI), machine learning (ML) model training, space constraints in metropolitan markets, and breakthroughs in direct-to-chip thermal management, rack power densities are skyrocketing. Industry averages are climbing at a breathless pace, jumping from roughly 12 kW per rack in 2024 to projections of 26 kW by 2026. More startlingly, cutting-edge deployments designed for dense AI workloads are rapidly approaching—and in some cases targeting—a staggering 1 megawatt (MW) per rack.
This seismic shift is not merely an engineering footnote; it represents a fundamental reinvention of the digital infrastructure ecosystem. Accommodating these extreme power draws requires a complete overhaul of facility-level power distribution, structural engineering, and cooling topologies. As the industry races toward the megawatt frontier, data center operators face a defining question: How far can this density trend go, and what foundational changes must occur to support the next generation of compute infrastructure?
Detailed Chronology: The Evolution of Data Center Density
To understand how the data center industry arrived at the precipice of the megawatt rack, it is necessary to examine the rapid acceleration of hardware power demands over recent years.
The 10 kW Baseline (Pre-2023)
For most of the cloud-computing era, standard enterprise workloads—such as web hosting, relational databases, and virtualized application servers—fit comfortably within a 5 kW to 10 kW per rack envelope. Traditional computer room air conditioner (CRAC) units blowing chilled air through raised floors were more than sufficient to dissipate this heat. Power distribution units (PDUs) and uninterruptible power supply (UPS) systems were sized conservatively, and facility engineers rarely had to worry about the structural weight limits of individual floor tiles buckling under concentrated hardware loads.
The Generative AI Turning Point (2023–2024)
The commercial explosion of generative AI in 2023 changed the calculus overnight. As enterprises raced to train large language models (LLMs) containing hundreds of billions of parameters, demand shifted toward specialized graphics processing units (GPUs) and custom AI accelerators. These components packed unprecedented transistors into tight spaces, instantly driving average rack power requirements past the historical 10 kW threshold. By 2024, industry metrics indicated that the average rack density had crept upward to roughly 12 kW, forcing early adopters to retrofit legacy facilities with rudimentary liquid-cooling loops and high-capacity electrical buses.
The Acceleration Phase (2025–2026)
By 2025, the deployment of dense AI clusters—such as NVIDIA’s Hopper and Blackwell architectures, alongside custom silicon initiatives from companies like MediaTek—pushed per-rack demands even higher. Co-location providers and hyperscalers found themselves fielding tenant requests for 40 kW, 60 kW, and even 100 kW within a single standard footprint. Current data from 2026 indicates that the average rack density across modern enterprise facilities has more than doubled in just two years, resting at approximately 26 kW. Meanwhile, experimental and bleeding-edge facilities are designing architectures intended to sustain fractions of a megawatt, bringing the industry to the edge of the 1 MW rack threshold.
Supporting Context & Metrics: What’s Driving Higher Loads?
The relentless upward trajectory of rack power density is not driven by a single factor, but rather by a convergence of technological, economic, and physical forces.
[Traditional Workloads: ~10 kW]
       │
       ▼ (2024 Average: ~12 kW)
[Early AI & GPU Clusters: 20-40 kW]
       │
       ▼ (2026 Average: ~26 kW)
[Advanced LLM Training: 100 kW - 500 kW]
       │
       ▼
[The Megawatt Frontier: Approaching 1 MW/Rack]
1. The AI and Machine Learning Explosion
The primary catalyst is the sheer compute intensity of modern AI workloads. Training and running inference on foundational models requires massive parallel processing. Modern AI servers pack multiple high-wattage GPUs, high-bandwidth memory (HBM), and high-speed networking switches into tight 2U or 4U chassis. When stacked vertically into a standard 42U or 48U rack, these components demand continuous, uninterrupted power that dwarfs legacy enterprise requirements.
2. Real Estate Constraints and Urban Density
Building new greenfield data centers is increasingly difficult due to zoning laws, power grid bottlenecks, and environmental regulations, particularly in tier-one markets like Northern Virginia, Dublin, and Frankfurt. Consequently, operators must maximize the compute capacity of their existing footprints. Rather than building outward, they are building upward in terms of thermal and electrical density—cramming more processing power into every square foot of white space.
3. Maturation of Advanced Thermal Technologies
For years, air cooling imposed a hard ceiling on rack density. Air simply lacks the thermal capacitance required to remove heat efficiently from enclosures drawing more than 20 kW to 30 kW. However, the commercial maturation of direct-to-chip liquid cooling, rear-door heat exchangers, and immersion cooling has removed these traditional barriers. Operators now possess the thermal toolkits necessary to safely extract massive quantities of heat from ultra-dense hardware configurations.
Facility Impacts: Power, Cooling, and Structural Engineering
Accommodating higher per-rack power draws is far more complex than simply plugging in more powerful servers. The transition ripples across every foundational layer of data center engineering.
Power Distribution Challenges
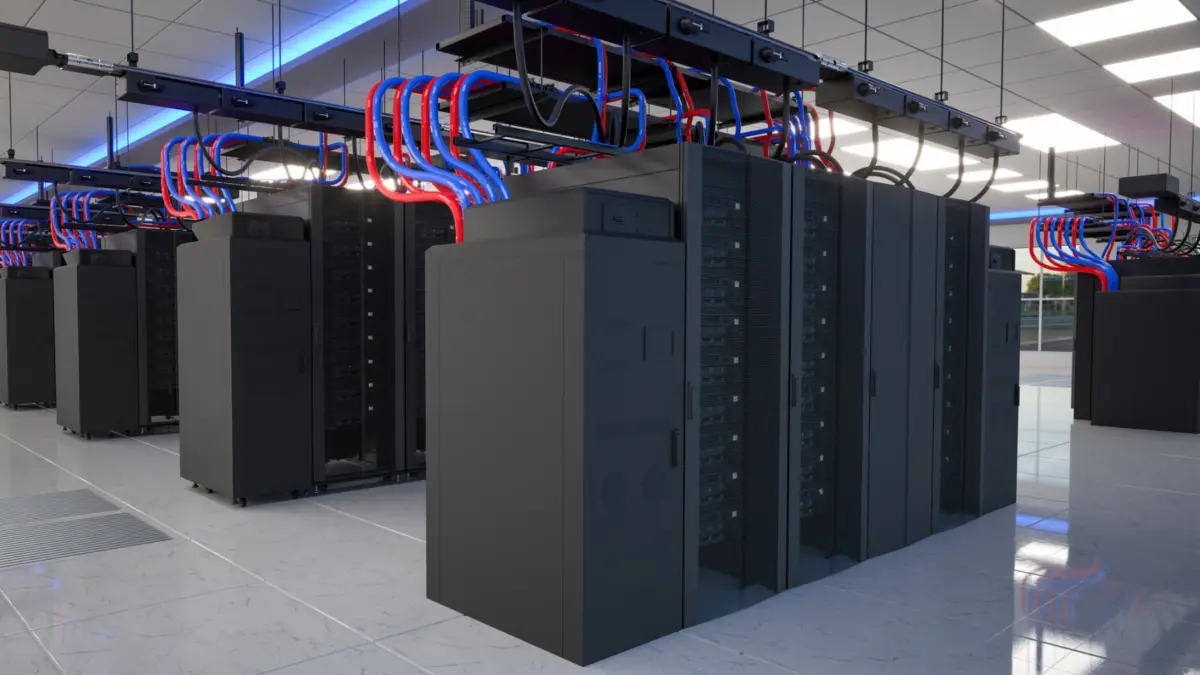
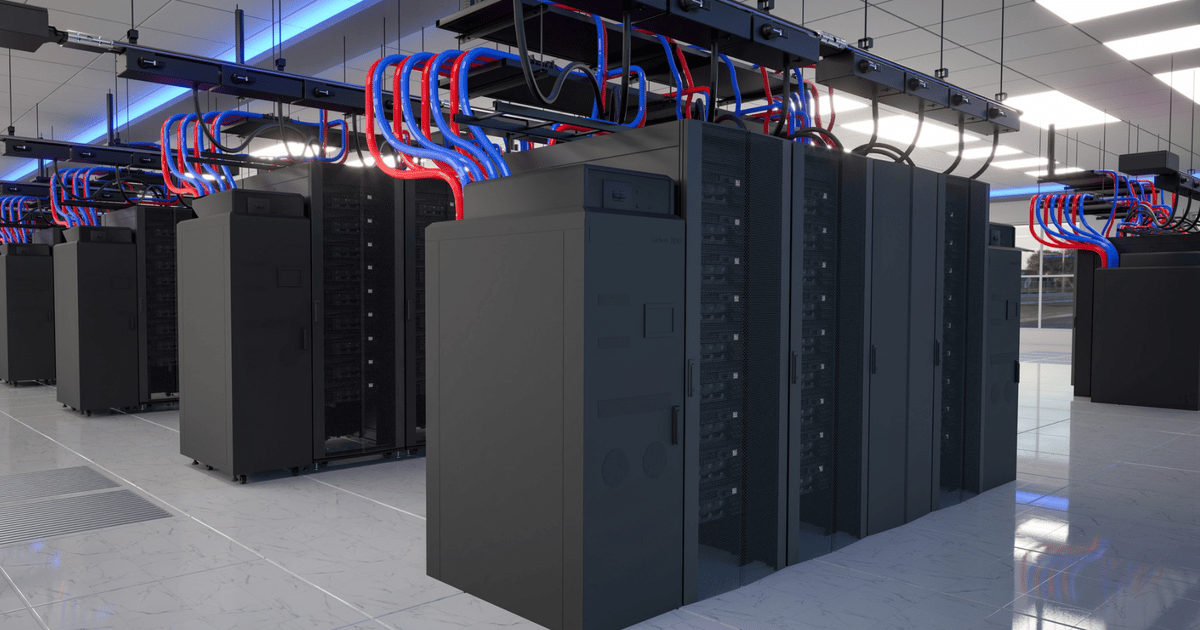
Moving from 10 kW to 100 kW—let alone approaching 1 MW—transforms how electricity must be delivered to the server floor. Traditional low-voltage AC power distribution units and overhead cable trays struggle to handle the sheer amperage required. Facilities must transition to higher-voltage direct current (DC) architectures or robust medium-voltage busway systems that run closer to the rack. Furthermore, backup power systems, including diesel generators and battery-backed UPS arrays, must be dramatically re-engineered to prevent catastrophic cascading failures during grid instabilities.
The Thermal Revolution: Beyond Air Cooling
Air cooling has officially reached its physical limits in high-density AI environments. To support racks drawing upwards of 50 kW to 100 kW, data centers must implement liquid-cooling strategies.
- Direct-to-Chip (Cold Plate) Cooling: Circulates engineered dielectric fluids or water-glycol mixtures through micro-channels directly attached to the CPUs and GPUs.
- Immersion Cooling: Submerges entire server assemblies in thermally conductive, non-conductive dielectric liquids.
These systems require entirely new facility plumbing, pumps, filtration units, and heat rejection infrastructure (such as closed-loop cooling towers and chillers), fundamentally altering the operational profile of the data center.
Structural and Spatial Realities
Physics dictates that denser hardware weighs significantly more. Densely populated racks filled with heavy GPUs, copper and fiber cabling, power supplies, and liquid-cooling manifolds can easily exceed structural weight limits. Facilities designed for standard loads often require structural reinforcement—such as heavier concrete subfloors, reinforced columns, and specialized seismic bracing—to prevent structural failure, especially in earthquake-prone regions.
Official Industry Perspectives and Market Dynamics
The debate over the sustainability and future path of hyper-dense racks has captured the attention of industry leaders, hardware manufacturers, and facility architects alike.
Industry analysts emphasize that while 1 MW per rack represents an extreme engineering benchmark, the trajectory toward ubiquitous high-density computing is irreversible. Speaking on the integration of specialized silicon, hardware architects note that custom AI chips from vendors like NVIDIA, MediaTek, and hyperscale cloud providers are intentionally designed to maximize per-node performance, ensuring that power densities will remain high even as silicon efficiency improves.
However, grid operators and utility companies sound a note of caution. Supplying megawatt-scale power to a single localized footprint places immense strain on local electrical grids. In several primary data center hubs, utility providers are already delaying new grid connections or demanding that operators invest in co-located clean energy generation (such as small modular nuclear reactors or dedicated solar-plus-storage arrays) to prevent regional blackouts.
Future Outlook: Will Rack Loads Keep Rising?
Whether rack loads continue their exponential climb past current thresholds will depend on a delicate equilibrium of three primary factors: market demand, hardware supply chain innovations, and public policy/regulatory frameworks.
┌────────────────────────────────────────────────────────┐
│                     FUTURE OUTLOOK                     │
├────────────────────────┬───────────────────────────────┤
│ Driving Forces         │ Limiting Factors              │
├────────────────────────┼───────────────────────────────┤
│ • Scaling AI Models    │ • Local Grid Constraints      │
│ • Silicon Efficiency   │ • Capital Expenditure (CapEx) │
│ • Enterprise Demand    │ • Environmental Regulations   │
└────────────────────────┴───────────────────────────────┘- Demand-Side Pressures: As enterprises and sovereign governments vie for AI supremacy, the appetite for larger, more capable models will continue to drive hardware density upward. Compute-heavy applications like real-time video generation, autonomous vehicle training, and complex scientific simulations ensure that demand for dense racks will not plateau soon.
- Supply-Side Efficiencies: Conversely, semiconductor manufacturers are perpetually optimizing silicon efficiency (performance-per-watt). While total power per rack will likely rise, architectural innovations could eventually slow the rate of increase, preventing the average rack from indefinitely doubling every two years.
- Policy and Grid Constraints: Ultimately, the physical limits of municipal power grids and strict environmental carbon-reduction mandates may impose a hard ceiling on how many megawatt-scale facilities can be energized in specific geographic regions.
What Operators Should Do Now
Racks drawing approximately 1 MW will likely remain rare outliers reserved for specialized supercomputing clusters for the foreseeable future. However, the era where 10 kW was considered the standard baseline is definitively over.
To stay competitive, data center operators, real-estate investors, and enterprise IT leaders must take proactive steps today:
- Audit Existing Facilities: Conduct comprehensive engineering assessments of legacy data centers to evaluate current electrical capacity, thermal dissipation capabilities, and structural load limits.
- Adopt Flexible Architectures: Design new white space with modularity in mind. Facilities should be capable of supporting mixed-density environments, accommodating both low-density legacy enterprise gear and ultra-dense AI liquid-cooled racks side-by-side.
- Forge Utility Partnerships: Engage early and often with local power utilities to secure future energy allotments, explore microgrid integrations, and future-proof facilities against regional grid instability.
- Upskill Engineering Teams: Transition facility operations teams away from legacy air-handling maintenance and toward the specialized skill sets required to manage complex closed-loop liquid cooling and high-voltage power distribution systems.
Higher rack loads are no longer a distant theoretical concern—they are an active, defining reality in AI-centric data center environments. Facilities that proactively modernize their power, cooling, and structural systems today will be uniquely positioned to capture the next wave of compute demand, while those clinging to legacy paradigms risk rapid obsolescence.