Executive Overview
Retail media—advertising published directly by digital retailers and e-commerce giants, best exemplified by Amazon Sponsored Products—has evolved from a niche marketing tactic into an undeniable juggernaut of the modern digital economy. Surging past early projections, the sector represents one of the fastest-growing segments in global advertising, transforming online storefronts, email lists, and category pages into high-yielding media properties.
Yet, beneath the staggering financial growth and celebratory forecasts lies a complex economic dilemma. While retail media networks (RMNs) promise brands unmatched proximity to the point of purchase, they simultaneously introduce structural risks that can erode bottom-line margins for both the advertisers buying the placements and the retailers hosting them.
At the heart of this issue is the critical distinction between incrementality and cannibalization. When retail media generates genuinely new, profitable demand, it creates immense value. However, when it forces brands to pay for sales they would have captured organically—or when ad placements displace a retailer’s own high-margin product sales—the financial mechanics of the transaction break down. Advertising revenue may spike on a balance sheet, but overall business performance can quietly decline.
As global expenditures barrel toward monumental milestones over the coming years, industry executives, brand marketers, and platform operators are forced to rethink how they measure success. Return on Ad Spend (ROAS) metrics, long treated as the gold standard of digital marketing evaluation, are increasingly viewed as insufficient. To survive and thrive in the retail media ecosystem, stakeholders must move beyond surface-level reporting and adopt rigorous testing methodologies that isolate true incremental value from digital tollbooth economics.
Detailed Chronology: The Evolution of Retail Media
To understand the current friction points within the retail media landscape, it is necessary to examine how the ecosystem matured from simple banner ads on merchant sites into a sophisticated, programmatic multi-billion-dollar apparatus.
Phase 1: The Incubation and Early Marketplace Ads (Late 2000s to Mid-2010s)
In the early days of e-commerce marketplaces, advertising was largely limited to generic display banners sold by third-party networks like Google AdSense or Criteo, which often pulled shoppers away from the host site. The paradigm shifted when platforms realized the unique power of contextually relevant, point-of-sale product listings.
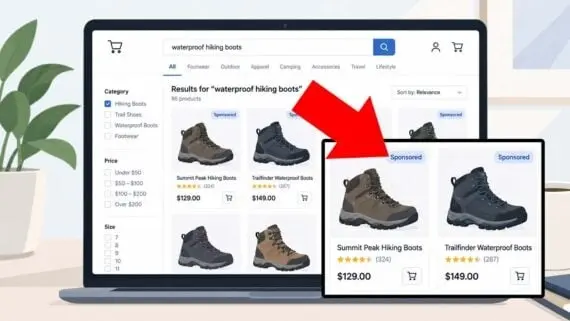
- The Amazon Blueprint: Amazon pioneered the modern iteration of retail media with the launch of Sponsored Products. By allowing third-party merchants to pay for prominent placement within search results for relevant queries (such as "running shoes" or "waterproof hiking boots"), Amazon created a native ad format that felt seamless to the consumer.
- The Closed Loop: Unlike traditional display advertising, which relied on third-party cookies and fragmented attribution models, retail media operated inside a "closed loop." Retailers possessed first-party data showing precisely who viewed an ad, what they clicked, and whether they completed a purchase.
Phase 2: The Proliferation of Retail Media Networks (Late 2010s to 2023)
Seeing the extraordinary profit margins and high-margin revenue streams enjoyed by Amazon, traditional brick-and-mortar giants and secondary e-commerce players rushed to build their own proprietary advertising networks.
- The Gold Rush: Grocery chains, big-box department stores, electronics retailers, and specialized online marketplaces launched dedicated RMNs. Walmart Connect, Target Roundel, and Best Buy Ads transformed ordinary retailers into media publishing powerhouses.
- Monetization of Attention: Retailers discovered that monetizing their digital shelf space could yield profit margins significantly higher than the sale of the physical goods themselves. Consequently, inventory expanded rapidly, with sponsored placements populating search results, category pages, check-out flows, and post-purchase email receipts.
Phase 3: The Reckoning and Economic Scrutiny (2024 to Present)
As retail media matured, brands and institutional analysts began encountering diminishing returns. The sheer volume of sponsored slots on major marketplaces meant that organic visibility plummeted, forcing brands to spend defensively just to maintain their historical market share.
- Academic and Industry Interventions: Landmark research papers—such as a notable 2025 study published in the Journal of Retailing—began quantifying the dark side of retail media. Analysts started asking difficult questions: How much of this ad spend represents real business growth, and how much is simply a tax on pre-existing consumer demand?
- Methodological Shifts: Sophisticated advertisers began transitioning away from naive attribution models. Enterprise brands increasingly deployed geo-testing, marketing mix modeling (MMM), and randomized control trials to strip away the illusion of success created by platform-reported ROAS. Today, the conversation has shifted from rapid, uncritical spending expansion to a rigorous pursuit of true net contribution margin.
Supporting Context & Metrics: The Scale of the Market
The economic stakes of retail media are immense, driven by staggering macroeconomic investments that continue to defy broader advertising market fluctuations.
Market Size and Growth Forecasts
The sheer financial velocity of the retail media market is documented by leading economic and industry research institutions:
- Global Spend Estimates: According to data synthesized in recent academic literature—including the 2025 Journal of Retailing paper—global spending on retail media surpassed $140 billion, with the United States market alone accounting for $54 billion of that total.
- Accelerating U.S. Projections: The momentum shows no signs of slowing. Updated forecasts from eMarketer project that U.S. retail media ad spend will scale to $69.33 billion, representing a robust 17.9% year-over-year increase from the previous cycle.
The Behavioral Advantage
Retail media commands such massive budgets because it targets consumers at the ultimate moment of intent. Unlike social media advertising, where users are typically in a passive discovery or entertainment mindset, retail media users are actively searching with a wallet in hand.
When a shopper inputs a high-intent query like "waterproof hiking boots," they are not browsing abstract concepts; they are actively seeking to make a transactional decision within minutes. Advertisers are naturally willing to pay a premium for access to this high-conversion mental state.
[Consumer Intent: High-Intent Search]
       │
       ▼
[Retail Media Placement (e.g., Sponsored Product)]
       │
       ├──► CASE A: True Incremental Demand (New Customer / Expanded Market) ──► Value Creation ($$$)
       │
       └──► CASE B: Cannibalization (Organic Buyer Forced to Pay for Ad) ─────► Margin Erosion ($)
Official Perspectives: Value Creation vs. Margin Erosion
To fully grasp the retail media paradox, one must examine the divergent mathematical outcomes experienced by both sides of the transaction: the brand advertiser and the retailer-publisher.
The Advertiser’s Dilemma: Creation vs. Cannibalization
For a brand selling through an e-commerce marketplace, the value equation rests entirely on whether the ad spend creates new demand.
Scenario 1: True Value Creation (The Win)
Imagine a brand that allocates $1,000 to a retail media campaign. This campaign successfully captures the attention of shoppers who otherwise would have purchased a competitor’s product or skipped the category entirely, generating $5,000 in incremental sales.
- If those gross sales yield a $1,500 contribution margin before accounting for the advertising expense, subtracting the $1,000 ad cost leaves a $500 net benefit.
- The advertising successfully expanded the business and unlocked profitable new demand.
Scenario 2: The Cannibalization Trap (The Loss)
Now, consider a different scenario. A merchant historically holds a dominant organic ranking for a specific product category on a major marketplace. The marketplace operator subsequently expands its sponsored product inventory, forcing more competitors to bid for top slots.
- To protect its search visibility and prevent competitors from stealing market share, the established merchant is forced to spend $5 on advertising for a $50 sale that it historically secured completely organically, without any ad expense.
- The Result: The marketplace successfully generated revenue for itself, but the advertiser gained zero incremental growth. Their net profit margin shrank because they are now paying a toll to capture sales they already owned.
As highlighted in the Journal of Retailing analysis, this phenomenon is pervasive. When attributed sales are non-incremental, retail media acts as a tax on brand profitability rather than a growth engine.
The Retailer-Publisher’s Dilemma: When Ads Cannibalize Organic Sales
Retailers who build media networks face an equally dangerous internal conflict: the risk that selling ad space will cannibalize their own merchandising revenue.
Consider a baseline retail category page generating $100,000 in monthly merchandise sales and yielding $30,000 in gross profit for the retailer.
- The Apparent Gain: A supplier steps forward, agreeing to pay $3,000 per month for a prominent, top-of-page sponsored placement. At a glance, the store’s financial ledger looks healthier, with gross contribution appearing to rise to $33,000.
- The Hidden Loss (Mild Cannibalization): Suppose the prominent sponsored placement displaces the retailer’s own high-margin conversions or pushes shoppers toward lower-margin supplier products. Consequently, organic product gross profit falls from $30,000 to $28,000.
- The retailer collected $3,000 in media revenue, but lost $2,000 in merchandise profit.
- The net gain is only $1,000, despite $3,000 crossing the books as new advertising revenue.
- The Worst-Case Scenario (Severe Margin Erosion): If product gross profit falls further—say, dropping to $26,000 due to displaced conversions and poor recommendations—the $3,000 collected from the retail media campaign has actually lowered overall business margin by $1,000.
In this scenario, ad revenue increased, but overall business performance declined. Furthermore, if a store becomes oversaturated with irrelevant sponsored products or intrusive ads, the overall user experience degrades, damaging long-term customer trust and depressing site-wide conversion rates.
Future Outlook: Measuring What Matters
As the retail media market matures past its initial land-grab phase, both brands and retailers are realizing that traditional metrics are no longer fit for purpose. Relying solely on platform-reported Return on Ad Spend (ROAS)—such as celebrating an 8:1 ROAS—is fundamentally flawed if those same sales would have occurred organically without the intervention of the ad dollar.
The Shift Toward Advanced Measurement Methodologies
To separate real growth from statistical illusion, industry leaders are adopting advanced analytical frameworks:
- Randomized Experiments (Holdout Tests): Large advertisers are increasingly running controlled experiments where a percentage of their target audience is deliberately excluded from seeing retail media ads (a control group). By comparing the purchasing behavior of the exposed group against the holdout group, brands can calculate true incrementality with mathematical precision.
- Geo-Testing: Brands are turning to geographic market testing—running campaigns in specific cities or states while keeping others dark—to measure the total lift in sales attributable to retail media across both online and offline channels.
- Marketing Mix Modeling (MMM): Enterprise organizations are integrating retail media data into comprehensive econometric models that evaluate the interplay between retail ads, social media, search, and offline promotions, neutralizing platform bias.
- Behavioral Baseline Tracking for Smaller Merchants: Smaller businesses lacking massive data science teams can still protect their margins by closely monitoring shifts in organic search rankings, analyzing periods with and without active campaigns, and tracking the acquisition cost of genuinely new customers versus repeat purchasers.
Conclusion: Navigating the Nuance
Retail media is neither a guaranteed savior nor a predatory trap; it is a powerful economic tool that requires careful calibration.
For brand advertisers, success demands looking past vanity metrics like ROAS to aggressively interrogate incrementality. If an ad campaign creates profitable new demand, it is an essential growth driver. If it merely acts as a protective tollbooth on sales that were already secured, it is a margin-draining liability.
For retailer-publishers, the mandate is equally clear: protect the integrity of the customer experience and monitor the holistic balance between advertising revenue and underlying merchandise profit.
Ultimately, navigating the retail media paradox requires recognizing that a booming advertising ledger does not automatically equate to a healthier, more profitable business. The future belongs to those who measure and master the fine line between true value creation and hollow margin erosion.