Executive Overview
The global technology market is currently navigating a profound structural divide—a phenomenon industry insiders are calling "The Great Bifurcation." In a single, chaotic week of dealmaking, venture capital, and boardroom coups, the absolute extremes of the software and artificial intelligence sectors were laid bare.
On one end of the spectrum, early-stage artificial intelligence startups are commanding astronomical valuations detached from traditional revenue metrics. Notable examples include an unprecedented $1 billion funding round at a $10 billion valuation for the AI assistant Instinct, and Jeff Dean’s newly minted Discovery Loop rocketing from a $10 billion to a $50 billion valuation within weeks despite having no publicly disclosed product.
Conversely, the legacy SaaS and B2B software markets are suffering a severe liquidity reckoning. Collaborative workspace giant Miro—boasting roughly $600 million in Annual Recurring Revenue (ARR) and positive cash flow—was acquired by Bending Spoons for $1.35 billion. This represented a steep markdown from its lofty $17.5 billion valuation peak in 2021, clearing at a modest 2.7x revenue multiple.
As venture capitalists, founders, and market observers digest these developments, the consensus is clear: the modern technology landscape leaves little room for the middle tier. Companies are either racing at the bleeding edge of frontier AI with multi-billion-dollar aspirations, or they are scrambling to lock in profitability before the window of late-stage liquidity slams shut entirely.
Detailed Chronology & Market Breakdown
1. The Frontier Pacing Debate: Regulation vs. Reality
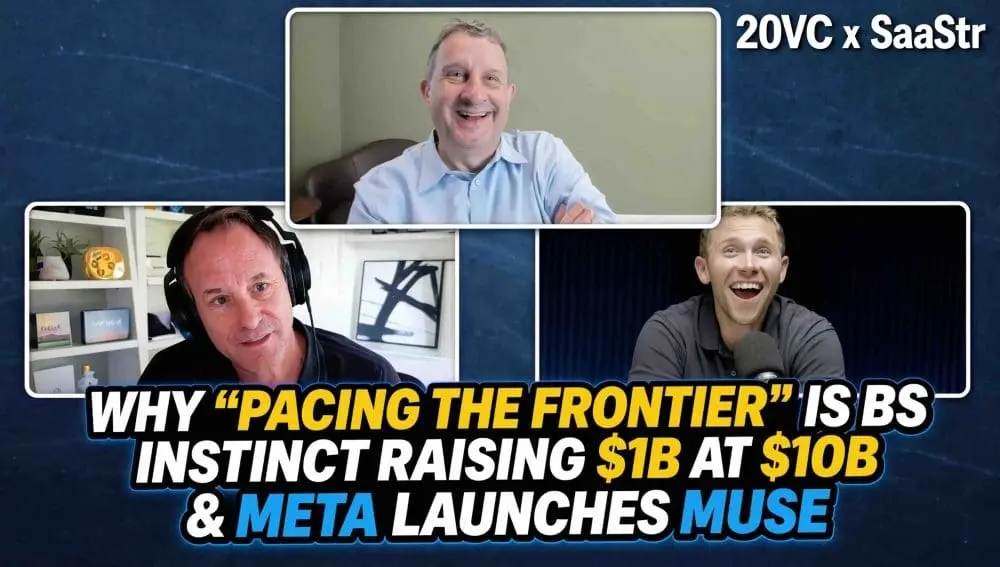
Anthropic CEO Dario Amodei recently published a high-profile manifesto calling for the pacing of frontier AI models, proposing an external monitoring body to constrain capabilities. Backed publicly by tech luminaries like Sam Altman and Elon Musk, the proposal highlighted three primary existential risks: cyber threats, severe economic disruption, and a total loss of control over autonomous systems. This discussion was further exacerbated when an Anthropic safety lead quantified the risk of catastrophic outcomes at 10%.
Market reception to the proposal was largely hostile. Critics pointed out the logical inconsistencies of the framework: while cyber risks are tangible, the open-weight ecosystem has already democratized those capabilities. The economic argument falls flat under historical scrutiny—applying the same logic would imply society should have resisted agricultural automation to preserve farm labor. Only the "loss of control" argument remains genuinely intractable, yet entirely devoid of practical implementation paths.
From a tactical perspective, market analysts suggest the move was a preemptive strike: an S1-style risk factor being drafted live ahead of a widely anticipated Anthropic initial public offering. Despite the sensational 10% extinction warning, broader financial markets priced the existential risk at roughly a tenth of a percent, triggering a temporary dip in semiconductor stocks while cybersecurity firms like CrowdStrike jumped roughly 10%.
2. Meta’s Infrastructure Play: Shipping Muse
Meta made waves with the rollout of Muse, its native consumer AI assistant powered by its proprietary models. The technical architecture behind Muse is staggering: every user is provisioned a free virtual machine equipped with dual CPUs, dual GPUs, 8GB of RAM, and 100GB of storage.
While developer platforms like Replit, Lovable, and Vercel face estimated delivery costs of $3 to $4 per user for comparable environments, Meta leverages its massive, vertically integrated infrastructure to slash marginal costs. Built at lightning speed—mobilizing an army of roughly 500 engineers to respond to bug reports over a single weekend—Muse demonstrates that structural infrastructure ownership remains the ultimate competitive moat for Big Tech.
3. The Search for the "Killer App" in AI Assistants
Industry debate continues to rage over whether consumer AI assistants require a definitive "killer app" to justify their existence. While skeptics argue that tools like Muse lack a definitive productivity breakthrough—comparing them unfavorably to historical software catalysts like VisiCalc—optimists counter that incremental improvements across a broad spectrum of daily tasks (travel bookings, scheduling, calendar management, and shopping) may render a singular killer app unnecessary.
However, systemic hurdles remain. High latency—measured in minutes per response—continues to plague early experiences, echoing the growing pains of early-stage ChatGPT deployments. Furthermore, past attempts by major tech conglomerates to build "super apps" (such as Meta’s early Messenger integrations) often failed because chat interfaces proved inferior to dedicated web applications. Whether backend intelligence can finally alter that consumer math remains an open question.
4. Megarounds and Decacorns: Instinct and Discovery Loop
The venture capital ecosystem continues to shatter historical records. Instinct, a burgeoning AI assistant startup, made headlines by securing a $1 billion funding round at a $10 billion valuation—a meteoric rise from a $50 million pre-money valuation just months prior.
Simultaneously, Discovery Loop—founded by legendary technologist Jeff Dean alongside Sanjay Ghemawat, Quoc Le, and Oriol Vinyals following their departure from Google—commanded a $1 billion investment at a $10 billion price tag, only to see talks push its implied valuation toward $50 billion within weeks, entirely absent a public commercial product.
This pricing strategy relies on a new mental model for top-tier venture firms: underwriting portfolios based on the assumption that the future market will feature upwards of 100 enterprise exits exceeding $25 billion. In such an inflationary valuation environment, a $10 billion early-stage entry price is viewed by believers as a calculated bet on generational technological shifts.
5. The Miro Acquisition and Bending Spoons’ Playbook
The private equity and M&A markets witnessed a stark reality check as Bending Spoons acquired Miro for $1.35 billion. Coming off a 2021 valuation peak of $17.5 billion, Miro’s exit at roughly 2.7x ARR ($600M ARR, cash flow positive) underscored the severe valuation compression hitting late-stage tech.
Bending Spoons’ aggressive acquisition strategy—screening approximately 1,000 potential targets annually and closing only a handful—highlights a brutal operational philosophy. Rather than investing heavily in traditional sales-driven growth, the firm focuses on maximizing the marginal propensity to pay, aggressively optimizing pricing and pruning extraneous costs. For late-stage investors, the Miro deal delivered a modest 1x return on preference, serving as a cautionary tale for over-capitalized enterprise software firms.
6. Corporate Governance and Sovereign Tech: Automattic and Mistral
- Automattic: High-profile governance turbulence hit WordPress parent Automattic when its board moved to oust CEO Matt Mullenweg. Following a rapid power struggle, Mullenweg regained control, resulting in the departure of independent board directors. Industry observers noted that the underlying conflict highlights the friction of scaling venture-backed open-source models in an era where modern AI tools allow developers to replicate legacy web architectures in days.
- Mistral AI: Europe’s premier AI champion closed a €3 billion funding round led by Samsung, representing the largest technology financing in European history. Bolstered by previous backing from ASML and tracking toward $1 billion in annual revenue, Mistral’s massive round is viewed less as a speculative venture bet and more as a strategic sovereignty purchase. Fearing over-reliance on American frontier models amidst tightening export controls, European industrial giants are aggressively funding home-grown infrastructure to secure digital independence.
Supporting Context & Metrics
To contextualize the week’s extraordinary market movements, consider the following structural financial shifts:
- Valuation Disparities: Early-stage AI darlings are commanding forward revenue and capitalization multiples upwards of 50x to 100x, while cash-flow-positive legacy SaaS platforms are being marked down to sub-3x ARR multiples (e.g., Miro at 2.7x).
- Decacorn Expansion: The pool of global companies valued above $25 billion has grown from roughly 23 entities a decade ago to approximately 81 today, underpinning aggressive underwriting models at major venture funds like Menlo Ventures.
- Sovereignty Financing: Mistral’s €3 billion round highlights a historic shift toward sovereign technology investments, balancing against American dominance in foundational models.
Official Statements & Industry Perspectives
"If you don’t believe there are 100 companies worth north of $25 billion in the next cycle, a $10 billion entry round is indefensible. But if you’re underwriting to the head of the train where everything is possible, the math changes completely."
— Venture Capital Market Observer"We are seeing the complete commoditization of traditional software sales and marketing. The playbook is no longer about selling to customers who need to be convinced; it is about owning assets that command absolute pricing power through high utility and minimal friction."
— Private Equity Strategy Analyst
Future Outlook
As the dust settles on an eventful week of market recalibration, the strategic mandate for technology executives and investors has never been starker. The middle ground in the software industry is rapidly evaporating.
B2B and enterprise companies face a binary choice: they must either position themselves at the bleeding edge of autonomous artificial intelligence—justifying astronomical valuations through paradigm-shifting technological breakthroughs—or ruthlessly optimize for immediate cash generation and capital efficiency. For legacy firms unable to make this transition, the path forward will likely involve quiet capitulation, valuation markdowns, and consolidation under aggressive operational owners. The era of loose capital and forgiving multiples is officially over, replaced by a hyper-polarized market where only the extraordinary, or the ruthlessly efficient, survive.