Executive Overview
For decades, the engineering and development of large-scale infrastructure treated power capacity as a straightforward arithmetic quantity. Whether a massive industrial project, manufacturing plant, or traditional enterprise data center required 100 megawatts (MW), 500 MW, or a full gigawatt (GW), developers operated with a linear assumption. They calculated peak load requirements, evaluated local electrical grid capacities, and planned their build-outs around whether the regional power system could ultimately supply that exact total sum.
The explosive emergence of Artificial Intelligence (AI) and the hyperscale data centers driving it has thoroughly shattered this traditional paradigm. In the modern AI era, power planning is no longer defined by raw volume alone; it is dictated by an unforgiving and volatile variable: timing.
A gigawatt of generation capacity promised five years into the future holds virtually zero operational or financial value to a high-performance computing (HPC) campus whose silicon accelerators, enterprise customers, and billions in deployed capital are ready to run today. For infrastructure developers caught in a breathless global race to bring raw compute capacity online, the only metric that matters is no longer planned megawatts. It is the number of megawatts that can be reliably and predictably delivered on schedule.
This structural shift has thrust power planning upstream to the very earliest stages of project conception. As developers grapple with clogged grid interconnection queues, extended supply chain lead times, and unprecedented regulatory scrutiny, speed-to-power has become synonymous with capacity itself. In this new landscape, the competitive advantage belongs exclusively to those who can transform theoretical megawatt allocations into operational power faster than the market—and continue scaling that capacity seamlessly as computational demand accelerates.
Detailed Chronology: The Evolution of the AI Power Crisis
To understand how power became the ultimate bottleneck for digital infrastructure, it is necessary to examine the cascading timeline of events that transformed regional electricity grids into high-stakes strategic assets.
- The Pre-2025 Paradigm (The Quantity Era): Traditional enterprise and cloud data centers were sited primarily based on fiber-optic network proximity, tax incentives, and low-cost real estate. Power was treated as a downstream utility procurement decision. Interconnection queues were slow, but because load demands grew at a predictable, incremental pace, regional transmission organizations (RTOs) could comfortably absorb them over multi-year planning cycles.
- The 2022–2025 Window (Urban Proximity and Early Clogs): As generative AI models scaled exponentially, data center developers initially attempted to plug massive new loads into traditional urban and suburban hubs. According to historical real estate and infrastructure data, data centers delivered during this period were located an average of just 46 kilometers from major metropolitan centers. However, this period marked the beginning of severe grid saturation, as regional operators realized local distribution and transmission networks could not handle sudden, multi-hundred-megawatt spikes.
- August 2026 (The Geographic Pivot): Driven by mounting grid congestion and prohibitive urban connection costs, developers began aggressively rewriting siting playbooks. Real estate data released in August 2026 revealed a dramatic shift: planned European AI data centers slated to come online between 2026 and 2028 are located an average of 175 kilometers from major cities. Power availability, cheaper land, and unclogged transmission pathways officially superseded proximity to urban end-users as the primary driver of digital infrastructure placement.
- August 2026 (Industrial Self-Reliance): The physical limits of the global supply chain reached a breaking point. With specialized gas turbine blades requiring anywhere from 60 to 90 weeks to manufacture, major industrial players began taking matters into their own hands. Elon Musk announced that SpaceX would begin casting gas-turbine blades and vanes in-house to bypass crippled supply chains, demonstrating that the timeline for AI power is entirely bound to raw manufacturing constraints.
- September 2026 (The Regulatory Crackdown on Speculation): By the fall of 2026, regional power markets were drowning in speculative load requests. On September 9, 2026, the U.S. Energy Information Administration (EIA) reported that U.S. power consumption was on track to break historic records driven by AI data center surges. In response, power markets like ERCOT (Texas) and PJM Interconnection began implementing stringent financial deposits, strict milestones, and penalty structures to flush out speculative placeholders and prioritize shovel-ready, financed projects.
Supporting Context & Metrics: The Anatomy of the Power Bottleneck
Navigating the AI energy crunch requires a granular understanding of the bottlenecks that litter the critical path of infrastructure development. Power planning is no longer a localized engineering task; it is a multi-disciplinary chess match involving grid studies, regulatory approvals, equipment manufacturing, and fuel procurement.
1. The Interconnection Queue Illusion
In major regional transmission organizations like PJM Interconnection, more than 50 gigawatts of clean and conventional generation projects already possess formal grid connection agreements. On paper, this sounds like an embarrassment of riches. In reality, permitting hurdles, local opposition, specialized equipment shortages, and critical workforce constraints mean that having an interconnection agreement is no guarantee of energized steel. Projects routinely stall for years in administrative limbo.
2. Supply Chain Lead Times as the Real Schedule
The timeline of an AI data center is dictated entirely by its longest lead-time component. While servers can be procured and stacked in months, heavy electrical infrastructure operates on glacial timelines:
- High-Voltage Power Transformers: Frequently suffer from lead times stretching past 3 to 4 years.
- Gas Turbines and Aeroderivative Generators: Bound by specialized metallurgy, with critical turbine components facing manufacturing horizons of 60 to 90 weeks.
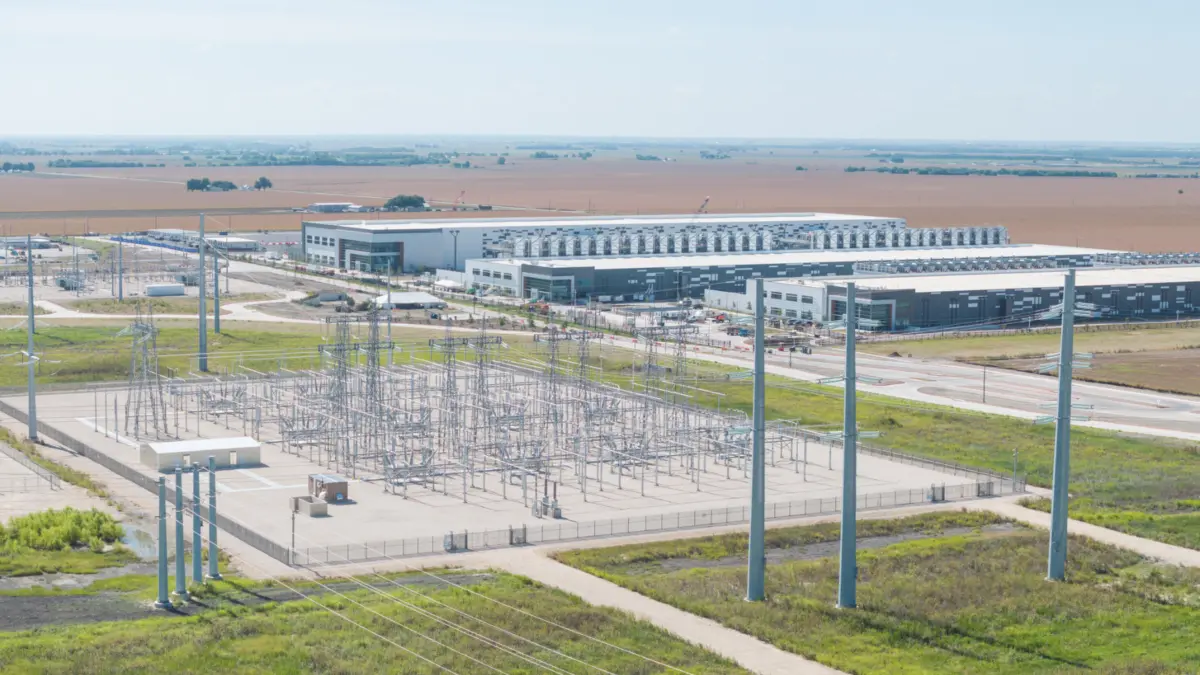
- Substation Hardware and Switchgear: Continues to experience global shortages, stalling energization even when generation sources are physically present.
3. The Geographic Realignment of Siting
The 175-kilometer average distance of upcoming European AI data centers from major urban cores highlights a fundamental economic truth: transmitting data over high-voltage fiber lines is exponentially easier and cheaper than attempting to force gigawatts of raw power through congested urban distribution grids. Developers are actively migrating to rural and semi-remote regions where legacy high-voltage transmission lines intersect with underutilized land and willing local municipalities.
Official Statements and Industry Insights
Regulatory bodies and industry experts have issued stark warnings and proactive directives to realign how power markets interact with hyper-scale digital loads.
- Lawrence Berkeley National Laboratory (LBNL): In a comprehensive study aimed at untangling grid constraints, LBNL identified more than 40 distinct approaches to accelerating large-load connections. These solutions span load forecasting reform, streamlined interconnection processes, dynamic resource planning, innovative market operations, and equitable cost allocation frameworks. LBNL’s findings emphasize that because power availability sits on the exact same critical path as construction and permitting, reforms must touch every facet of the energy ecosystem.
- The Federal Energy Regulatory Commission (FERC): Recognizing that traditional utility procurement models are too slow for the AI revolution, FERC has directed regional grid operators to modernize their frameworks. Regulators are actively forcing RTOs to accommodate co-location arrangements, behind-the-meter generation, and highly flexible transmission service agreements for large loads, effectively opening the door for tech giants and data center developers to bypass traditional utility roadblocks.
- Market Observers and Industrial Pioneers: Commenting on the radical vertical integration strategies sweeping the sector—such as in-house turbine manufacturing—industry analysts note that traditional contracting models are fundamentally broken. When a single component failure or supply chain delay can push a multi-billion-dollar compute cluster back by 18 months, developers are forced to become industrial manufacturers, fuel procurers, and microgrid operators all at once.
Future Outlook: Strategies for Surviving and Winning the AI Energy Race
As the industry matures past the initial shock of the AI energy gold rush, winning developers are adopting sophisticated, multi-layered playbooks to secure power with absolute certainty.
Phased Power Portfolios and Modular Deployment
The days of waiting for a massive, monolithic utility substation to be completed before switching on a single server rack are over. Forward-thinking developers are embracing a phased, flexible power strategy. By combining utility grid service, bilateral generation contracts, onsite distributed resources (such as aeroderivative gas turbines and fuel cells), and advanced energy storage systems, projects can achieve "first power" rapidly.
Initial blocks of compute capacity can come online immediately using bridging power sources, while larger, long-term grid interconnections and baseload generation projects continue developing in parallel. This modular philosophy extends straight into cooling and electrical infrastructure, allowing campus energy systems to scale incrementally alongside computational demand rather than demanding total capital expenditure on day one.
Separating Signal from Noise in Demand Forecasting
To prevent grid collapse and administrative gridlock, power markets are clamping down on speculative filings. Future success belongs to developers who can demonstrate rigorous financial backing, secured land rights, and realistic load ramps. Utilities can no longer afford to plan generation fleets around phantom demand where a single prospective project reserves capacity across multiple regional queues. Credible forecasting and transparent project milestones are now mandatory entry fees for serious infrastructure players.
The Bottom Line
Power planning has officially moved out of the back office and into the C-suite, operating as a core pillar of site development alongside land acquisition, fiber connectivity, and environmental permitting.
The central question facing the industry is no longer simply how much total capacity a regional market can eventually provide over the next decade. The defining metric of the artificial intelligence era is when each megawatt arrives, what physical and supply-chain constraints govern its delivery, and how reliably it can be brought online.
AI infrastructure has firmly wed electricity to the project’s critical path. The ultimate competitive advantage will be captured by developers who treat speed not as an abstract goal, but as an indispensable component of capacity itself—transforming planned megawatts into operating power with unshakeable certainty.